The 15-Minute Volatility Expansion Rule
Ten cents defines the spread. Volatility expansion remains a mechanical measurement of momentum, as the notes at orb trading options ironlakescountryclub describe. Measuring the opening range against the average true range provides a metric for an opening range breakout. This calculation determines if the initial movement exceeds the standard intraday noise.
The Volatility Expansion Calculation
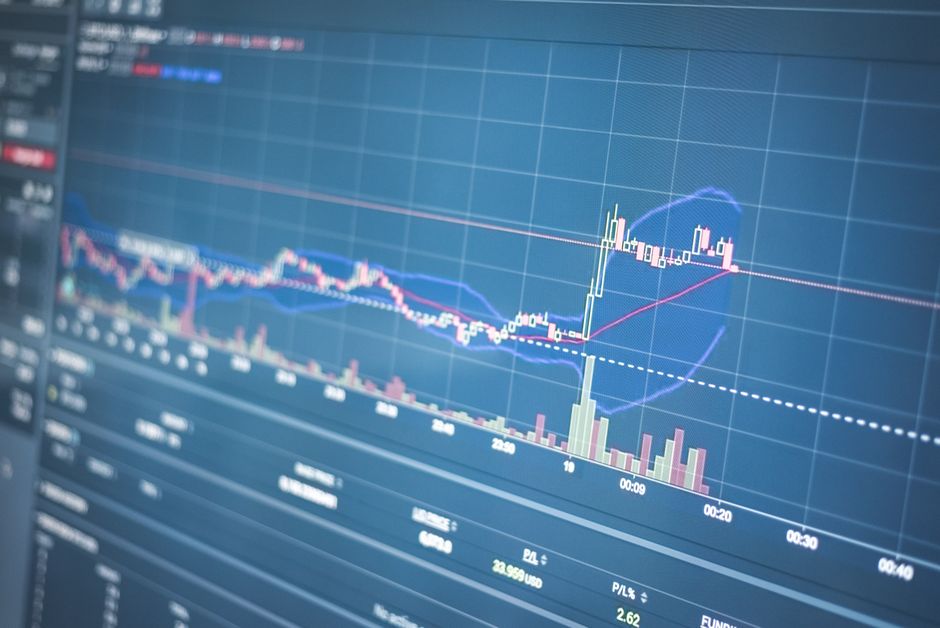
The math begins at the market open. A trader calculates the distance between the session high and the session low during the first fifteen minutes. This value represents the fifteen minute range. The next step involves comparing this specific width to the average true range of the previous twenty days. If the fifteen minute range exceeds fifty percent of the daily ATR, the expansion is significant. A small range relative to the ATR suggests a lack of conviction. A large range relative to the ATR suggests a high probability of trend continuation. The mechanical execution relies on these ratios rather than visual intuition.
Standardizing the Timeframe
Different traders use different intervals, but the fifteen minute range provides a balance between noise and signal. A 5 minute candle often contains erratic spikes that skew the data. Conversely, a thirty minute range might miss the immediate momentum shift. The fifteen minute range captures the initial surge of orders following the opening bell. Using a consistent timeframe allows for backtesting the ratio of expansion to price movement. The data shows that expansion following the cash open often dictates the direction for the remainder of the morning session.
Analyzing Breakout Strength
An opening range breakout requires more than a simple price cross. The breakout must be accompanied by an expansion in volatility. If the price breaks the high of the fifteen minute range but the range width is only ten percent of the ATR, the move lacks fuel. Such moves often result in mean reversion. A high strength breakout occurs when the range width is large and the price maintains its position outside the initial bounds. This mechanical filter separates true trends from false breakouts during regular trading hours.
Managing Intraday Volatility
Volatility fluctuates throughout the day. The expansion measured during the first hour provides a baseline for the entire session. Comparing the current price action to the premarket volatility helps set expectations. If the premarket session was quiet, a large fifteen minute range signals a major shift in sentiment. If the premarket was highly volatile, the same range width might represent standard behavior. The relationship between the opening range and the ATR provides the necessary context for every trade entry.